Almost everyone who applies for coverage worries about the wrong part. They brace for the needle and the blood pressure cuff, then find out the slow stretch was a doctor's office taking three weeks to fax over a file. The life insurance underwriting process is the carrier's way of deciding two things: whether it will insure you at all, and at what price. Knowing the order it happens in, and which parts you actually control, makes the whole thing far less stressful.
- Underwriting runs in five stages: application, consents and record pulls, the paramed exam, the underwriter's review, and the offer.
- Carriers commonly quote four to six weeks, though healthy applicants in accelerated programs may hear back in days.
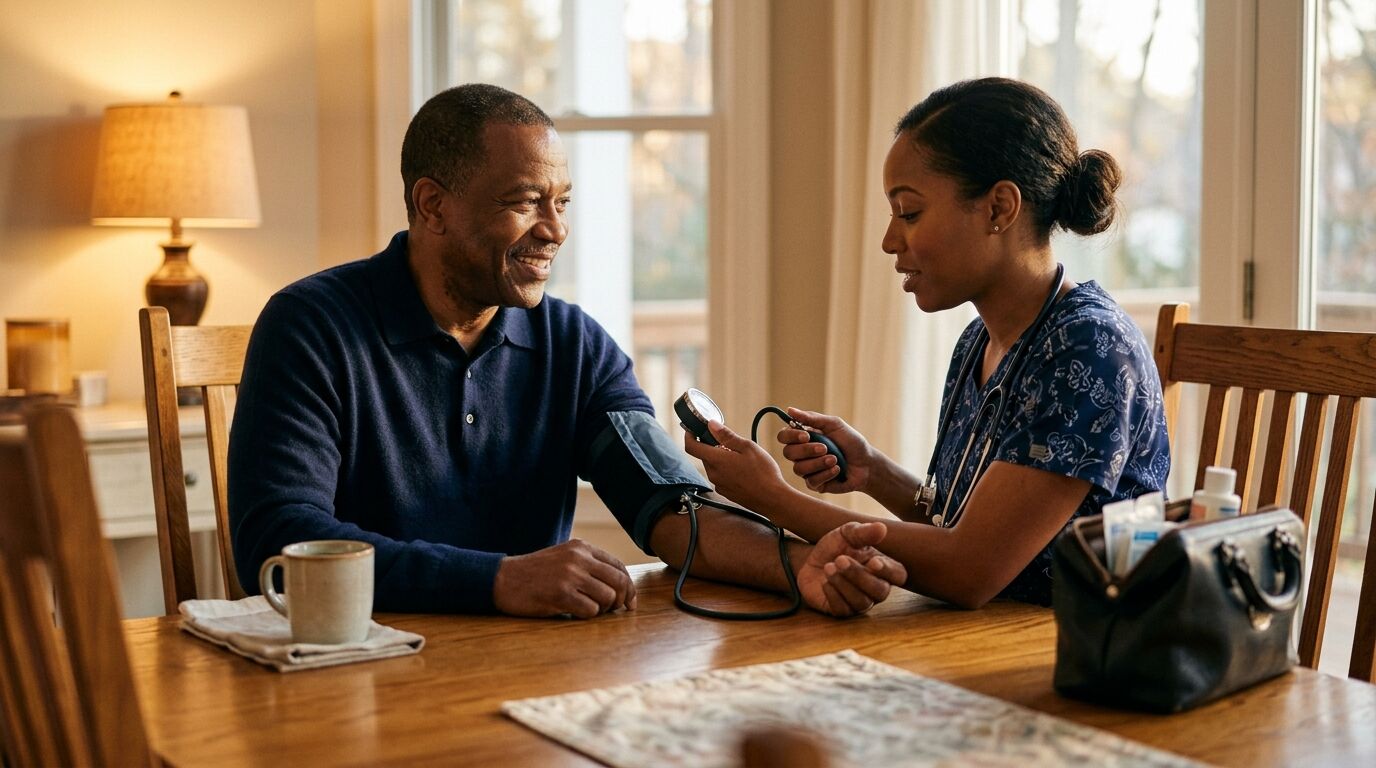
- The exam is a paramedical visit at your home or office, usually under 30 minutes, and the carrier pays for it.
- Your answers get checked against prescription history, medical records, the MIB and your driving record, so accuracy matters more than speed.
- An offer that comes back above standard is a starting point, not a verdict. Guidelines vary by carrier.
What the Life Insurance Underwriting Process Actually Is
Underwriting is risk assessment. The carrier is trying to estimate how long you're likely to live, using the same kinds of information a doctor and an actuary would each find useful, and then price the policy so the pool of people who look like you stays solvent for decades.
That estimate turns into a rate class, which is the single number that drives your premium. Two people the same age applying for the same death benefit can pay very different amounts because one landed in a preferred class and the other didn't.
One thing worth clearing up early: your agent isn't the underwriter. We help you decide how much coverage you need and which carrier is likely to look at your file most kindly, we put the application together, and we advocate for you while it's under review. The underwriter is a separate specialist inside the insurance company who never meets you.
The Five Stages, Start to Finish
1. The application
This is the longest sit-down of the whole thing, usually 30 to 60 minutes. You'll answer questions about your personal and family medical history, prescriptions and dosages, surgeries and hospital stays going back several years, tobacco or nicotine use, alcohol, height and weight, occupation, hobbies, upcoming international travel, and your finances.
The financial questions surprise people. Carriers require what's called financial justification for the amount you're asking for, because coverage has to bear some sensible relationship to what would actually be lost. If you're unsure what that number should be, our guide on how much coverage you need walks through the math before you ever fill out a form.
2. Consents and the record pull
You'll sign a HIPAA authorization and a few related consents. Those let the carrier request your medical records, look at your prescription history through a pharmacy database, order a motor vehicle report, and query the MIB, an industry exchange that flags information reported on previous applications.
This stage is where most delays live. The carrier can order records in an afternoon. A busy medical practice may take two or three weeks to send them.
3. The paramed exam
A paramedical examiner comes to your home or office at a time you pick, usually for 20 to 30 minutes. The carrier pays. There's no bill to you and no copay.
Some applicants skip this entirely. Accelerated underwriting programs use prescription, claims and public-record data in place of fluids, and they're generally aimed at healthy applicants under about 60 and under a certain face amount. According to the NAIC's overview, state regulators have been building guidance around how carriers use that data. We wrote separately about the tradeoffs in no exam coverage, since skipping the exam isn't free.
4. The underwriter's review
Now a person reads the file. They're looking for consistency between what you said, what your records show, and what the labs came back with. A condition you disclosed and manage well is rarely a problem. A condition the records show and the application didn't mention is a problem, and not mainly because of the condition.
If something needs clarification, the underwriter sends back a requirement. That might be an attending physician's statement, a short follow-up questionnaire, an EKG, or a request to re-test one lab value. Requirements are normal. They're not a signal that you're being turned down.
5. The offer
The file closes with a decision: approved as applied for, approved at a different class or with a table rating, approved with a modification such as a lower face amount, postponed, or declined. You'll see the rate class and the premium that goes with it. Nothing is binding until the policy is delivered and the first premium is paid, so you can still decline the offer or take it to another carrier.
What the Paramed Exam Actually Measures
The visit itself is unremarkable. The examiner records your height, weight, pulse and blood pressure, asks a short set of health questions, and collects blood and urine.
The labs generally look at:
- Cholesterol and the lipid panel, including the ratio between total cholesterol and HDL
- Blood sugar and A1c, which show how glucose has been running over the past few months rather than just that morning
- Liver and kidney function markers
- Nicotine and cotinine, which is how carriers separate tobacco rates from non-tobacco
- Certain drugs of abuse
- Proteins and other values that can point to something worth a closer look
Older applicants and larger face amounts may add an EKG, a treadmill test, or a cognitive screen. A few practical notes that genuinely help: schedule it early in the morning, skip the workout the day before, go easy on salt and alcohol for a few days, drink water so the blood draw goes smoothly, and avoid caffeine that morning. You can't renovate your health in a week, and no one expects you to. You can avoid handing the lab a bad day.
The exam is a photograph, not a biography. It captures where your numbers are the morning the examiner shows up.
How Long Life Insurance Underwriting Takes
Four to six weeks is the expectation most carriers set for a fully underwritten policy. Healthy applicants in accelerated programs may get an answer within a few days. Complicated files with several record requests can run longer.
What actually moves the clock:
- Doctor's offices. Record retrieval is the most common holdup by a wide margin.
- Scheduling. Booking the paramed exam in the first week instead of the third shortens everything downstream.
- Completeness. A missing dosage or a doctor's address you couldn't remember turns into a follow-up call days later.
- Face amount. Larger policies bring more requirements and sometimes a second set of eyes.
If you have a deadline, say so up front. A loan closing, a divorce decree or an expiring term policy all give us a reason to ask for a rush and to pick carriers known for turning files around quickly.
Rate Classes and What Moves You Between Them
Class names vary by company, but most carriers use some version of this ladder: Preferred Plus at the top, then Preferred, Standard Plus, Standard, and then table ratings for applicants with meaningful health history. Tobacco use puts you on a parallel ladder with its own, higher pricing.
What typically moves someone down a rung is build (the height and weight relationship), blood pressure or cholesterol that isn't controlled, a family history of early cardiac disease or certain cancers, a driving record with recent serious violations, or a health condition that's still being worked up.
What matters more than the label: the difference between two adjacent classes can be meaningful over a 30-year term, and it's close to permanent on a policy you intend to keep for life. That's part of why we spend real time on carrier selection before the application goes in. If you're weighing the two structures, our comparison of term and whole life covers what's at stake beyond the first year's premium.
Why an Honest Application Beats a Fast One
Every consent you sign opens a window into records you may have forgotten about. Prescription databases go back years. The MIB carries coded flags from previous applications. Motor vehicle reports are a phone call. Leaving something out rarely hides it.
The real exposure comes later. Most policies carry a contestability period of roughly two years from issue, and rules vary by state. During that window, if the carrier discovers a material misstatement on the application, it can rescind the policy or deny a claim. That's the scenario nobody plans for, because the person who filled out the form isn't there to explain it.
Full disclosure also gives an underwriter something to work with. A condition that's diagnosed, treated and well managed often reads better than a vague answer, because the file shows a person who's on top of their health.
When the Offer Comes Back Rated or Declined
A rated offer isn't a dead end. Options usually include:
- Take it, then ask for a review later. Many carriers will reconsider a rating after a year or two of documented improvement, and some will remove it.
- Shop the file. Underwriting guidelines differ. A condition one company tables another may write at standard.
- Adjust the design. A smaller face amount, a different product, or splitting coverage across two policies can bring the premium back into range.
- Wait it out. Some postponements are about timing, such as a procedure scheduled or a test still pending.
Working with an independent agency helps here, because we can place the same file with several carriers rather than defending one company's answer. If you want to understand where coverage fits alongside the rest of a household plan, our family protection strategies page lays out how the pieces connect.
How to Make the Process Go Smoothly
Before you start, gather your driver's license, a current list of medications with dosages, the names and addresses of doctors you've seen in the last five years, and dates for any surgeries or hospital stays. Having that in one place cuts the application time roughly in half.
Then schedule the exam early, answer everything completely, and expect a follow-up question or two. Underwriting isn't a test you pass or fail. It's a file being built, and a complete file moves faster than a flattering one.
If you'd rather not guess at any of this, book a time with us and we'll walk through what your file is likely to look like before anything gets submitted. Knowing the likely outcome in advance is usually worth more than a fast application.
Let's protect what you're building.
Every family's situation is different. Start with a conversation. No pressure, just clear answers about the coverage that fits your life.
Book an appointmentThis article is for educational purposes only and is not financial, tax, or legal advice. Product features, guarantees, and tax treatment vary by policy and carrier and are subject to the terms of the issuing company. Guarantees are based on the claims-paying ability of the issuer. Please consult a licensed professional about your specific situation.